


EN
The Bull Case For Burlington (BURL) Could Change Following Strong Q4 Beat And Aggressive Store Expansion Guidance
- In early March 2026, Burlington Stores reported fourth-quarter sales of US$3,642.5 million and net income of US$310.39 million, with diluted EPS from continuing operations rising to US$4.84, alongside full-year revenue of US$11.57 billion and EPS of US$9.51.
- Management paired these results with guidance calling for high single-digit to low double-digit sales growth and plans to open 110 net new stores, underscoring a continued emphasis on physical expansion and operating leverage.
- Next, we’ll assess how Burlington’s stronger-than-expected fourth-quarter results and raised full-year outlook may reshape its prior investment narrative.
Capitalize on the AI infrastructure supercycle with our selection of the 35 best 'picks and shovels' of the AI gold rush converting record-breaking demand into massive cash flow.
Burlington Stores Investment Narrative Recap
To own Burlington Stores, you have to believe its off price model and aggressive store growth can keep drawing value focused shoppers into physical locations, despite industry shifts toward digital. The latest quarter’s strong sales and earnings, together with higher full year guidance, support the near term catalyst of continued operating leverage from new stores, but they also amplify the key risk that an expanding fixed cost base could hurt results if traffic softens or the consumer weakens. Overall, this news materially reinforces the existing thesis rather than changing it.
The most relevant update is Burlington’s plan to open 110 net new stores alongside its raised outlook, which directly ties into the company’s expansion driven catalyst. This step signals management’s continued confidence in capturing value seeking demand through bricks and mortar growth, while also heightening exposure to store level risks such as higher labor costs and potential pressure on merchandise margins if tariffs or sourcing constraints re emerge. For investors, the pace and productivity of this expansion will be critical to watch against the backdrop of...
Read the full narrative on Burlington Stores (it's free!)
Burlington Stores' narrative projects $14.3 billion revenue and $993.7 million earnings by 2028. This requires 9.1% yearly revenue growth and about a $447.3 million earnings increase from $546.4 million today.
Uncover how Burlington Stores' forecasts yield a $343.07 fair value, a 12% upside to its current price.
Exploring Other Perspectives
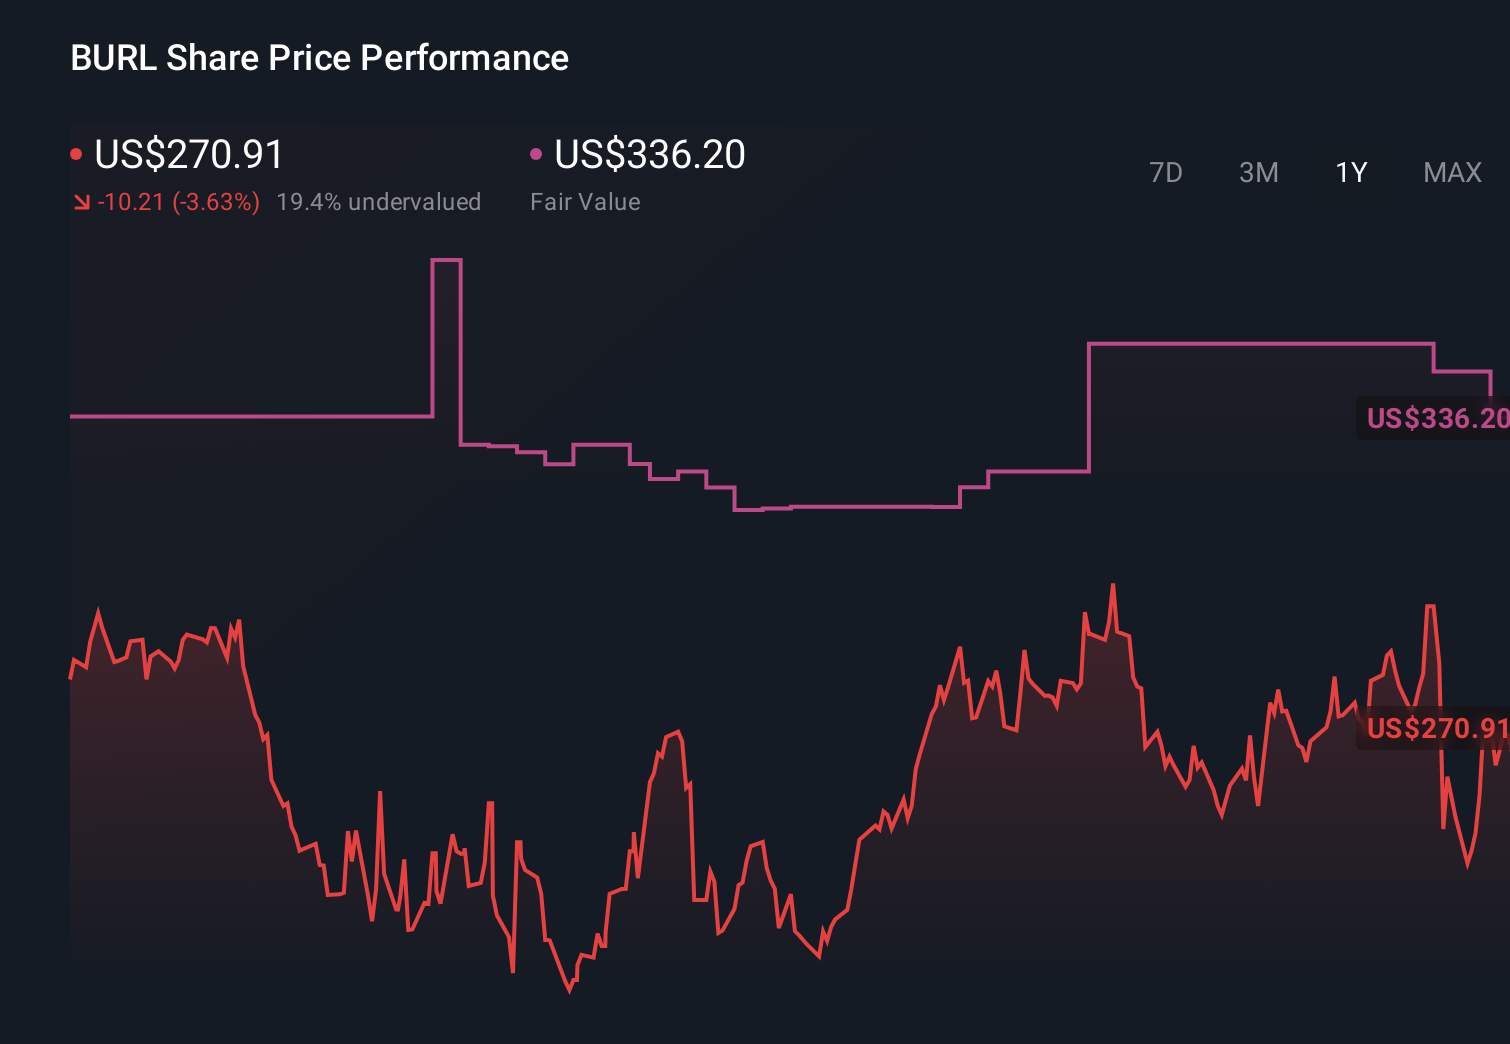
Four fair value estimates from the Simply Wall St Community span roughly US$175 to US$343 per share, showing how widely individual expectations can vary. Against this wide range, Burlington’s emphasis on rapid store expansion and operating leverage means your view on its physical growth plans may strongly shape how you interpret those valuations and the company’s future performance, so it helps to compare several of these perspectives side by side.
Explore 4 other fair value estimates on Burlington Stores - why the stock might be worth as much as 12% more than the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Burlington Stores research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- Our free Burlington Stores research report provides a comprehensive fundamental analysis summarized in a single visual - the Snowflake - making it easy to evaluate Burlington Stores' overall financial health at a glance.
Looking For Alternative Opportunities?
Markets shift fast. These stocks won't stay hidden for long. Get the list while it matters:
- Outshine the giants: these 20 early-stage AI stocks could fund your retirement.
- Invest in the nuclear renaissance through our list of 85 elite nuclear energy infrastructure plays powering the global AI revolution.
- The future of work is here. Discover the 28 top robotics and automation stocks leading the charge in AI-driven automation and industrial transformation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com